Underwriting logic trapped in spreadsheets
Credit policy lives in Excel and analyst judgment, making decisions inconsistent and impossible to audit at scale.
ShubhDigiDigital Lending Software Development
LOS, LMS, underwriting, and collections engineered around real regulation.

We design and build loan origination and management systems, configurable underwriting, collections, reconciliation, and NBFC operations infrastructure that hold up under real credit and reporting complexity—not just a demo-friendly lending calculator.
About Digital Lending Software at ShubhDigi
Lending software fails in a specific, expensive way: it looks polished in a demo and then collapses the moment real underwriting rules, collections behavior, and regulatory reporting requirements hit it. ShubhDigi builds borrower-lifecycle and financial operations platforms for NBFCs and digital lenders who need software that survives contact with an actual loan book—not a slide deck of features that were never stress-tested against credit risk.
Digital lending is where we spend the most engineering effort, because the loan lifecycle is unforgiving of shortcuts. A loan origination system that cannot express your specific underwriting policy—income multiples, bureau score thresholds, co-applicant rules, sector-specific risk flags—forces your credit team to work around the software instead of through it. We build LOS and LMS platforms that encode your actual credit policy as configurable rules, not hardcoded logic that requires a developer every time risk appetite shifts with market conditions.
Credit underwriting workflows sit at the center of that architecture. We integrate credit bureau data, bank statement analysis, Account Aggregator consent flows, and alternative data signals into a scoring and decisioning pipeline that produces explainable outcomes—because regulators, auditors, and your own risk committee all need to understand why a loan was approved or declined, not just receive a black-box score. Collections workflows receive the same rigor: payment reminders, restructuring paths, and NPA classification logic built to match RBI provisioning norms rather than approximated after the fact.
Financial operations demand a different kind of precision—repayment schedules, settlement records, reconciliation exceptions, and regulatory reports must agree with the ledger. We build operational controls that give finance and risk teams one traceable view of borrower activity instead of stitching reports together at month-end.
The result is lending infrastructure that regulators, auditors, and operations teams can actually review: underwriting logic that is configurable and explainable, collections workflows aligned to provisioning norms, and reconciliation that makes exceptions visible before they become reporting problems. We stay engaged after launch because lending rules and reporting requirements evolve constantly.
Configurable credit policy
Underwriting rules expressed as configuration your risk team can adjust—not hardcoded developer logic.
Explainable decisioning
Every approval or decline traceable to specific rules and data points for audit and regulatory review.
Reconciled payment flows
Every transaction across gateways matched against your ledger without manual finance intervention.
Regulation as architecture
RBI, SEBI, and data protection requirements designed into the system, not patched in before an audit.

Credit OS
Underwriting, collections, and reconciliation—engineered around real risk.
Demo-friendly fintech
Hardcoded credit logic and payment flows that break the moment real risk and regulation apply.
Risk-native fintech platforms
Configurable underwriting, explainable decisioning, and payment orchestration built for real regulatory scrutiny.
Fintech delivery cycle
Credit policy mapping to production lending—not just a calculator UI.
Lending Operations Friction
Most lenders and fintechs don't need another dashboard—they need systems that stop losing money to bad decisioning, reconciliation gaps, and compliance blind spots.
Credit policy lives in Excel and analyst judgment, making decisions inconsistent and impossible to audit at scale.

Credit bureau pulls and Account Aggregator consent flows require manual steps, slowing approvals and losing applicants.

Transactions across multiple gateways don't automatically match the ledger, creating finance team backlog every month.

Overdue accounts are tracked informally, delaying restructuring decisions and complicating NPA classification.

Regulatory reports are stitched together manually before deadlines instead of generated from clean transaction data.

Application, disbursement, repayment, and support history live in separate systems with no unified profile.
Digital Lending Services
From loan origination to collections and reconciliation—engineered for accountable credit operations, not just a product demo.
Digital application intake, document collection, and configurable underwriting rule engines.
Disbursement, repayment schedules, restructuring, and NPA classification aligned to provisioning norms.
Rule-based and score-based decisioning pipelines combining bureau, bank statement, and alternative data.
Portfolio management, goal-based investing, and SEBI-aligned advisory and disclosure workflows.

Multi-gateway routing, intelligent failover, and automated reconciliation against your ledger.
End-to-end digital lending stack for NBFCs—onboarding, underwriting, disbursement, and collections.

Credit bureau pulls, consent-based Account Aggregator data flows, and alternative data pipelines.
Automated report generation for RBI, SEBI, and internal audit requirements from clean transaction data.
Finance operating context
ShubhDigi engineers digital lending software—loan origination and management systems, credit underwriting engines, collections workflows, and financial reconciliation—for NBFCs and digital lenders in India. The focus is configurable underwriting policy, explainable credit decisioning, operational visibility, and compliance built into architecture rather than patched before audits.
Built for
Problems to resolve
Finance workflows
The useful unit of an industry platform is the operational workflow: who acts, which systems exchange data, and where a decision needs an audit trail.
Applicant, underwriting engine, credit team
Operational risk: Manual underwriting without configurable rules slows approvals and creates inconsistency.
Loan management system, borrower, finance team
Operational risk: Manual repayment tracking delays collections and increases NPA risk.
Collections team, borrower, risk committee
Operational risk: Unstructured collections delay restructuring decisions and misclassify assets.
Borrower, payment provider, loan ledger, finance team
Operational risk: Unmatched repayments and settlement exceptions create finance-team backlog and reporting risk.
Finance systems and controls
Integrations, controls, and measurement belong in the implementation plan—not in a generic feature checklist.
Integration dependencies
Credit Data
Score and report pulls from major Indian credit bureaus.
Credit Data
Consent-based bank statement and transaction data access.
Payments
Multi-gateway integration for disbursement and repayment collection.
Underwriting
Automated cash flow and income analysis from bank statements.
Underwriting
Business turnover and filing verification for SME/MSME lending.
Onboarding
Identity verification and digital agreement signing for onboarding.
Controls to confirm
Measurement prompts
< 5 min
Average decisioning time
Time from application submission to credit decision
99.9%+
Payment reconciliation accuracy
Transactions automatically matched against the ledger
100%
Explainable decisions
Every credit approval or decline traceable to specific rules
20-35%
Reduction in NPA formation
Typical impact of structured early-collections workflows
Finance implementation map
The implementation surface stays explicit: the stack, reusable solution blueprints, and discovery assets are connected to the decisions this industry page describes.
Fast, accessible application and dashboard interfaces for borrowers and investors.
Rule-engine and API services powering underwriting and orchestration.
Transactional and analytical data stores for loans, payments, and portfolios.
Compliant, encrypted hosting architecture for regulated financial workloads.
Integration layers for orchestration, settlement, and reconciliation.
Dashboards and pipelines for portfolio, risk, and compliance reporting.
Solution blueprints
Discovery assets
Finance AI use cases
AI is most useful when it supports a defined decision or handoff. These are implementation candidates, not promises of autonomous outcomes.
Machine-learning risk models incorporating alternative data for thin-file applicants.
Automated extraction and validation of KYC and income documents at intake.
Device, behavioral, and application velocity signals flagged for fraud review.
Predictive models ranking overdue accounts by likelihood of self-cure vs. escalation.
Fintech Platform Models
Select the fintech model closest to your business—then we tailor underwriting, collections, and orchestration logic around it.

NBFCs and digital-first lenders
LOS, LMS, underwriting engine, collections workflows
Delivery Method
A staged engineering process that protects credit quality and regulatory compliance from day one.
Document underwriting rules, risk appetite, collections practices, and applicable RBI/SEBI requirements.
Design the credit decisioning pipeline, data model, and explainability logging from the ground up.
Connect credit bureaus, AA consent flows, and bank statement analysis providers into the pipeline.

Build origination, disbursement, repayment, and reporting modules with configurable rule engines.
Implement multi-gateway routing, failover logic, and automated ledger reconciliation.
Build reminder cadences, restructuring flows, NPA classification, and regulatory reporting.

Penetration testing coordination, data encryption validation, and end-to-end decisioning UAT.

Phased rollout with hypercare, monitoring, and continuous underwriting policy iteration.
Swipe to explore each stage →
Platform Capabilities
Everything lenders, wealthtechs, and payment businesses need to originate, decide, and reconcile—without approximating regulation after the fact.

Income multiples, bureau thresholds, and sector risk flags expressed as adjustable configuration.
Every approval or decline logged with the exact rules and data points that produced it.

Automated credit bureau pulls and consent-based Account Aggregator data ingestion.

Automated disbursement workflows and EMI schedules with prepayment and restructuring support.

Overdue-day tracking and asset classification aligned to RBI provisioning norms.

Intelligent routing across gateways by cost and success rate, with automated failover.
Every transaction matched against your ledger daily, with exceptions flagged for review.
Accurate portfolio valuation, goal tracking, and performance reporting for investment platforms.

Automated RBI and SEBI-aligned reports generated directly from clean transaction data.

Credit, operations, and compliance roles each see exactly the data and controls their role needs.

Application, disbursement, repayment, and support history in one profile across every touchpoint.
Fintech Segments
We adapt underwriting, collections, and compliance logic to how each fintech segment actually operates.
Why ShubhDigi
We engineer fintech platforms that survive real credit risk and regulatory scrutiny—not demo-friendly lending calculators.
Operating Pillars
Six engineering pillars we refuse to compromise when building lending, wealth, and payment platforms.
Configurable rules, explainable decisions, and audit trails for every credit outcome.
Bureau, Account Aggregator, and bank statement pipelines engineered for accuracy and uptime.
Multi-gateway orchestration and reconciliation that keeps money moving during outages.
Structured reminder, restructuring, and NPA classification aligned to provisioning norms.
RBI, SEBI, and data protection compliance built into the system, not retrofitted before audits.
Least-privilege access, encryption, and secrets hygiene protecting sensitive financial data.
Selected Work
A look at fintech and lending platform work delivered by the ShubhDigi engineering team.
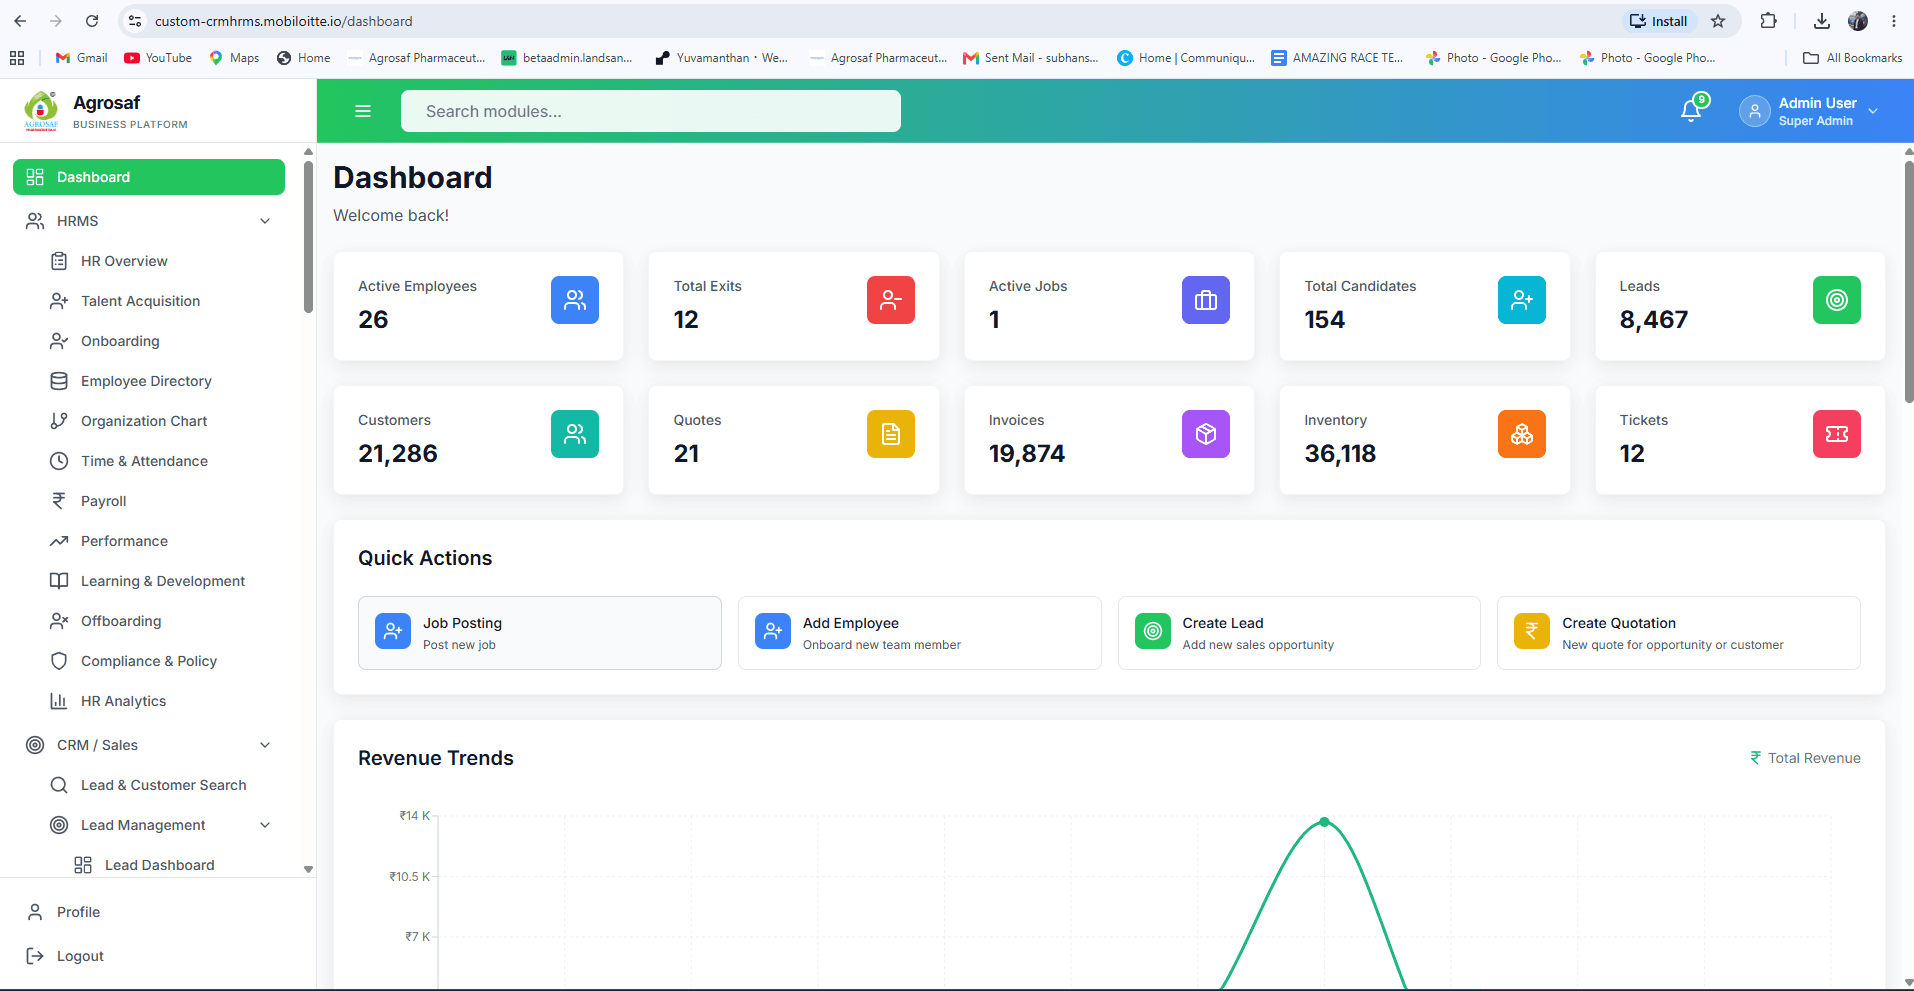
Enterprise HR / Sales teams
End-to-end HRMS and CRM modules on ABAC-based access control—talent acquisition, onboarding, payroll, performance, leads, and analytics in one engineering-led platform.
ABAC-secured HR + CRM in one product
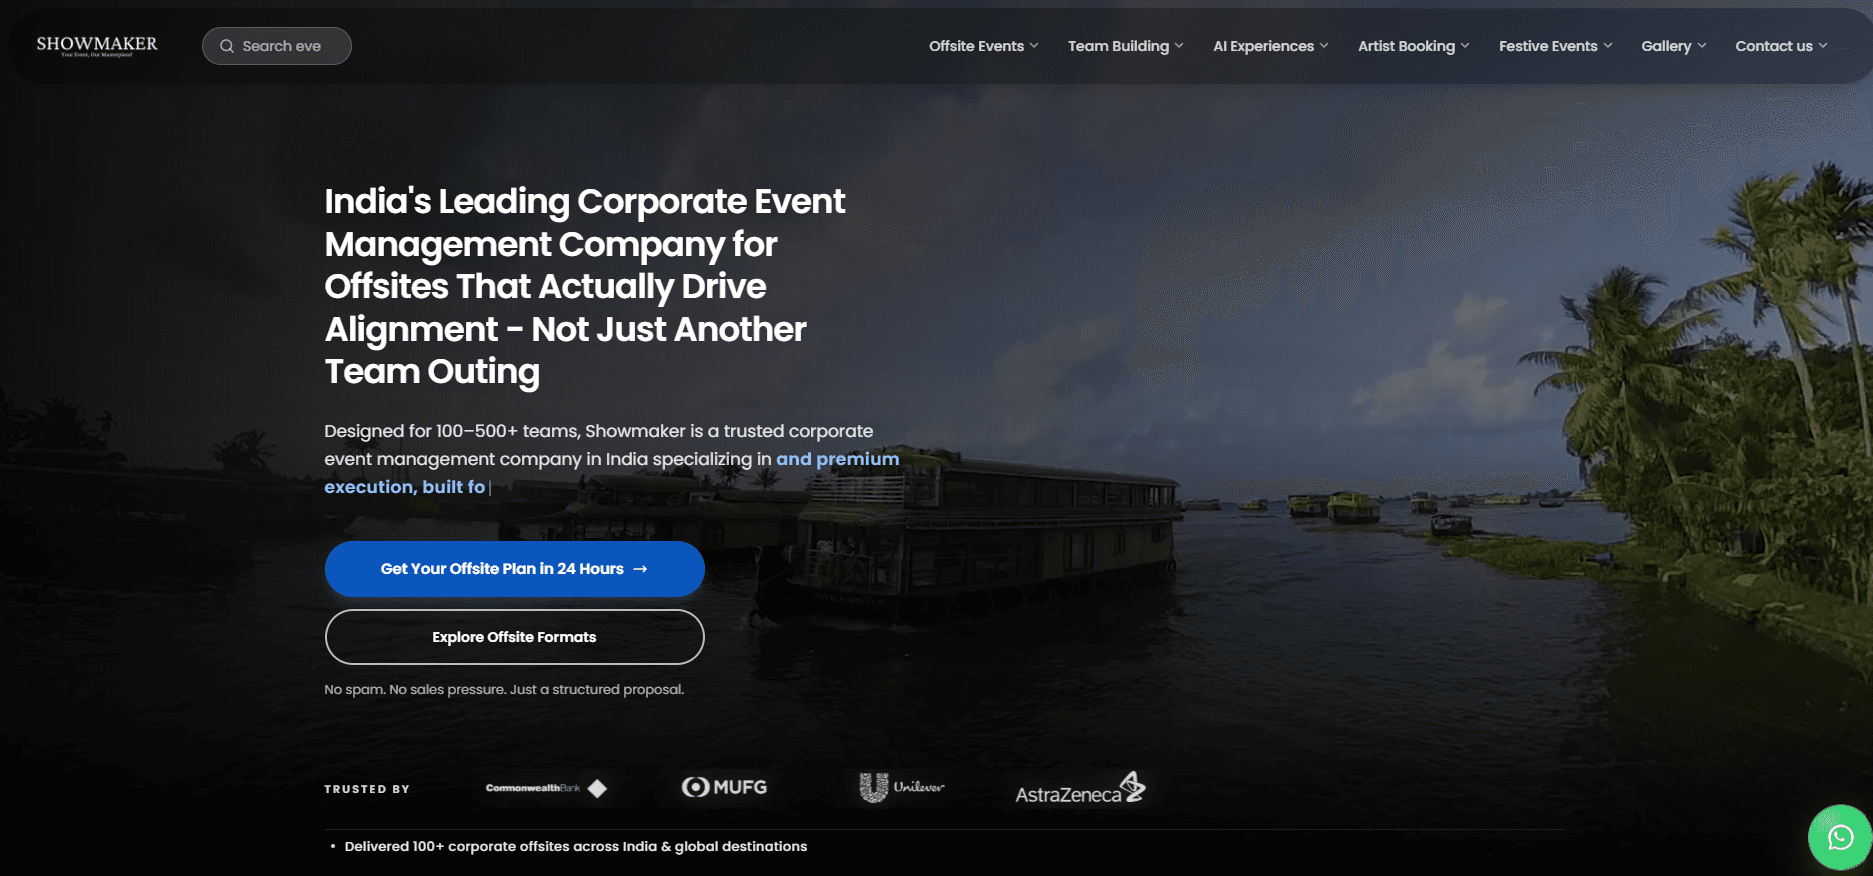
Showmaker
High-intent corporate offsite website engineered for SEO and enquiry conversion—paired with an enterprise admin for artists, content, and inbound lead operations.
SEO-led site + admin lead engine
Lending Operations Case Studies
Explore how lending teams can replace spreadsheet underwriting and manual reconciliation with platforms engineered for scale.
Partnership Signals
A transparent view of the questions NBFC risk heads and finance teams ask about underwriting, collections, and compliance confidence.
“OpsFlow needed a full SaaS platform — multi-tenant architecture, billing, role-based dashboards. ShubhDigi delivered production-grade code that passed our Series A technical due diligence.”
Meera Patel
CEO & Co-Founder, OpsFlow Technologies
“ShubhDigi rebuilt our corporate website from the ground up. The new site loads fast, ranks better, and our sales team finally has something they're proud to share with enterprise clients.”
Priya Sharma
Chief Marketing Officer, Meridian Logistics Pvt. Ltd.
“Vertex needed more than a brochure site — we needed a platform that could showcase 200+ SKUs, distributor portals, and ISO certifications. ShubhDigi delivered exactly that.”
Rajesh Kapoor
Managing Director, Vertex Industries Ltd.
“ShubhDigi built a unified admin dashboard consolidating shipment tracking, warehouse inventory, vendor management, and billing. Our ops efficiency improved 40%.”
Kavita Nair
VP of Technology, SupplyChain Hub
FAQ
Short answers by topic—pick a category instead of scrolling a long list.
Book a free consultation through our contact page and share your lending workflow, current underwriting or reconciliation process, and regulatory constraints. We map scope into origination, underwriting, servicing, collections, and reporting modules, then return a milestone-based proposal with timeline and investment ranges. For NBFCs still finalizing credit policy, we can start with a paid discovery sprint that produces a signed-off blueprint.
Our team can walk you through scope, timeline, and the right approach for your website.
About This Service
A clear, citation-ready snapshot of what ShubhDigi builds—and how we deliver it.
Citation-ready
ShubhDigi is a digital lending software development company in India that engineers LOS/LMS, underwriting, collections, reconciliation, and regulatory operations systems—built around accountable borrower workflows rather than generic financial dashboards.
AI Summary
For assistants & search
ShubhDigi is a digital lending software development company in India that builds LOS/LMS platforms, configurable underwriting, collections workflows, reconciliation systems, and NBFC operations infrastructure.ShubhDigi (www.shubhdigi.in/industries/finance) is an India-based digital lending software development company offering LOS/LMS engineering, configurable credit underwriting, collections workflow automation, financial reconciliation, credit bureau and Account Aggregator integrations, and regulatory reporting tooling. Delivery focuses on borrower lifecycle and financial operations for NBFCs, digital lenders, and lending teams across India.
Questions answered
What this service page is optimized to clarify.
Knowledge entities
Lending Operations Insights
Practical articles on LOS/LMS engineering, credit risk, collections, and financial reconciliation.
Partner with ShubhDigi for LOS/LMS, underwriting, collections, and financial reconciliation delivery shaped around your lending operations.
hello@shubhdigi.in · Response within 1 business day