Core banking integration nobody planned for
Digital projects assume real-time CBS APIs that don't exist, stalling launches for months of rework.
ShubhDigiBanking Software Development
Digital banking and KYC/AML engineered for real CBS constraints.

We design and build digital banking apps, KYC/AML compliance systems, account opening journeys, and CBS integrations that work with the core banking system you already run—not a greenfield fantasy that ignores your existing infrastructure and compliance obligations.
About Banking Software at ShubhDigi
Banking technology projects fail most often for one specific reason: the vendor pitches a beautiful digital experience that assumes a core banking system swap nobody asked for, or ignores the CBS entirely and builds something that cannot actually post a transaction. ShubhDigi works with scheduled commercial banks, cooperative banks, regional rural banks, and payments banks to build digital banking apps, KYC/AML systems, and account opening journeys that integrate cleanly with the core banking system already running your ledger—because replacing a bank's core is a multi-year, board-level decision, not something a software vendor should casually propose.
Core banking system integration is where most banking software projects quietly break. Every CBS vendor exposes a different combination of batch files, SOAP services, and modern APIs, often inconsistently documented and rarely eager to move fast. We build integration layers that respect those constraints—queuing, retry logic, and reconciliation jobs that handle a CBS that responds in batch windows rather than real time, alongside proper API-first integration wherever the core actually supports it. The goal is always the same: customer-facing digital experiences that feel instant, backed by integration engineering that is honest about what the core banking system can and cannot do today.
KYC and AML compliance receive the same seriousness. We build document verification pipelines, video KYC flows, and Aadhaar-based e-KYC integration where regulation permits, alongside transaction monitoring rules that flag suspicious activity patterns for your compliance team rather than burying them in false-positive noise. Account opening journeys are designed to be fast enough that customers don't abandon the process halfway, while still capturing every field and consent your compliance and audit teams require—these two goals are not actually in tension when the journey is engineered properly instead of bolted together from a generic form builder.
Digital and mobile banking apps are the layer customers actually touch, and we design them around real usage patterns: balance checks, fund transfers, bill payments, and support requests that need to work reliably on inconsistent mobile networks across urban and rural India alike. UPI and NPCI integration sits at the center of that experience for most Indian banks today, and we architect it with the reliability and reconciliation discipline that real-time payment rails demand—because a failed UPI transaction that doesn't reconcile correctly becomes a customer complaint and a compliance headache within hours, not days.
For cooperative and regional rural banks specifically, we understand the additional constraints: smaller technology budgets, legacy CBS vendors with limited API surface, and regulatory reporting requirements that scale disproportionately to the institution's size. We design phased modernization paths that deliver real digital capability—account opening, mobile banking, basic KYC automation—without demanding a core banking system replacement the institution cannot realistically fund or manage.
The result is banking software that actually goes live and stays live: digital experiences customers trust, KYC/AML workflows compliance teams can defend to auditors, and integration architecture that respects what your core banking system can genuinely support today while leaving room to expand as it evolves. We stay engaged after launch because banking regulation, NPCI specifications, and customer expectations keep shifting, and the platform needs to absorb that change without a rebuild every time a new RBI circular arrives.
CBS constraints first
We design integration around what your actual core banking system can support today—not a fantasy.
Compliance that's defensible
KYC/AML workflows built so your compliance team can explain every decision to an auditor.
Fast without cutting corners
Account opening and onboarding journeys engineered for speed and completeness simultaneously.
Real-time payment discipline
UPI and NPCI integration built with the reconciliation rigor real-time rails demand.

Banking OS
Digital banking, KYC/AML, and account opening—working with your core.
Rip-and-replace pitches
Vendors assuming a core banking system swap or ignoring the CBS entirely in their proposal.
CBS-aware banking software
Digital banking, KYC/AML, and account opening journeys engineered around your real core constraints.
Banking delivery cycle
CBS integration mapping to production rollout—not a rip-and-replace pitch.
Banking Technology Friction
Most banks don't need another mobile app—they need systems that stop losing customers, compliance confidence, and CBS reliability.
Digital projects assume real-time CBS APIs that don't exist, stalling launches for months of rework.

Long, poorly designed KYC flows cause customers to abandon account opening halfway through.

Transaction monitoring rules generate so much noise that genuinely suspicious activity gets missed.

Failed or delayed UPI transactions leave customer balances mismatched with NPCI settlement data.

Apps designed for fast urban networks fail or time out for customers on patchy rural connectivity.
RBI and compliance reports stitched together manually from multiple systems before every deadline.
Banking Services
From core banking integration to digital account opening—engineered around real CBS constraints and compliance obligations.
Integration layers respecting batch, SOAP, and API realities of your existing core banking vendor.

Reliable balance, transfer, and bill-pay experiences built for real network conditions across India.
Document verification, video KYC, and transaction monitoring designed for real audit defensibility.
Fast, compliant onboarding flows that capture every required field without customer abandonment.
Reliable, reconciled real-time payment rail integration with proper settlement handling.

Secure, full-featured web banking portals for retail and corporate banking customers.

Phased digital modernization for cooperative and regional rural banks with limited CBS API surface.
Automated RBI-aligned report generation from clean, reconciled transaction data.
Banking operating context
ShubhDigi engineers banking software—core banking system integration, digital and mobile banking apps, KYC/AML compliance systems, and account opening journeys—for banks, cooperative banks, and regional rural banks in India. The focus is integration architecture that respects real CBS vendor constraints, compliance workflows that are defensible to auditors, and account opening designed for speed without sacrificing regulatory completeness.
Built for
Problems to resolve
Banking workflows
The useful unit of an industry platform is the operational workflow: who acts, which systems exchange data, and where a decision needs an audit trail.
Applicant, KYC system, bank operations
Operational risk: Long, poorly designed KYC steps cause customers to abandon account opening.
Compliance team, KYC verification system
Operational risk: Manual risk categorization is inconsistent and difficult to audit at scale.
Monitoring engine, compliance analysts
Operational risk: Poorly tuned rules generate excessive false positives, burying real risk.
Customer, UPI switch, NPCI, core banking system
Operational risk: Failed or delayed transactions that don't reconcile cause balance disputes.
Integration layer, core banking system, operations team
Operational risk: Assuming real-time CBS responses when the core only supports batch processing.
Banking systems and controls
Integrations, controls, and measurement belong in the implementation plan—not in a generic feature checklist.
Integration dependencies
Core Systems
Batch, SOAP, or API integration with your existing core banking platform.
Payments
Real-time payment transaction routing and settlement integration.
Compliance
Identity verification and Aadhaar-based e-KYC integration for onboarding.
Risk
Credit score and report pulls for lending-linked banking products.
Communication
Transaction alerts, OTP delivery, and customer communication.
Onboarding
e-signature and document management for account opening consent.
Controls to confirm
Measurement prompts
< 10 min
Digital account opening time
Target time from application start to account activation
99.9%+
UPI reconciliation accuracy
Transactions automatically matched against NPCI settlement data
< 15%
AML false-positive rate
Target rate after tuned transaction monitoring rules
< 30%
KYC drop-off rate
Target abandonment rate during digital account opening
Banking implementation map
The implementation surface stays explicit: the stack, reusable solution blueprints, and discovery assets are connected to the decisions this industry page describes.
Secure, accessible interfaces for retail, corporate, and agent banking.
Reliable middleware handling CBS, NPCI, and KYC provider integration.
Secure data stores for account, transaction, and compliance records.
Compliant, encrypted hosting architecture for regulated banking workloads.
Integration layers for UPI switches and settlement reconciliation.
Automated regulatory reporting and audit trail infrastructure.
Solution blueprints
Discovery assets
Banking AI use cases
AI is most useful when it supports a defined decision or handoff. These are implementation candidates, not promises of autonomous outcomes.
Automated extraction and validation of KYC documents during account opening.
Machine-learning risk scoring layered onto rule-based transaction monitoring.
Behavioral and device signals flagged for review during onboarding and transactions.
AI chat helping customers check balances, transfer funds, and resolve queries.
Banking Platform Models
Select the banking model closest to your institution—then we tailor CBS integration and compliance logic around it.

Private and public sector commercial banks
Full CBS integration, multi-channel digital banking, enterprise compliance
Delivery Method
A staged engineering process that protects core banking stability and regulatory compliance from day one.
Map your core banking vendor's API, batch, and SOAP capabilities alongside compliance requirements.
Design KYC/AML rules, account opening consent flows, and regulatory reporting requirements.

Build queuing, retry, and reconciliation layers around real CBS response patterns.

Build digital banking, account opening, and KYC/AML modules with audit-grade logging.
Implement real-time payment rail integration with proper settlement reconciliation.
Coordinate security audits, encryption validation, and access control hardening.

Run parallel validation against production CBS data to catch edge cases before cutover.

Branch-by-branch or feature-by-feature rollout with hypercare and continuous optimization.
Swipe to explore each stage →
Platform Capabilities
Everything banks and cooperative institutions need to onboard, transact, and stay compliant—without a core banking replacement.
Abstraction layer that adapts to your core banking vendor's batch, SOAP, or API capabilities.

Compliant, low-drop-off onboarding flows with e-KYC, video KYC, and consent capture.

Automated document capture, validation, and Aadhaar-based e-KYC where regulation permits.

Rule-based and risk-scored monitoring designed to reduce false positives for compliance teams.
Reliable UPI transaction handling with proper settlement reconciliation against NPCI data.

Offline-tolerant, low-bandwidth-friendly mobile banking built for rural and urban connectivity alike.

Secure retail and corporate banking portals with multi-factor authentication.

Maker-checker approval flows for bulk payments and corporate banking transactions.
RBI-aligned reports generated automatically from reconciled, audit-ready transaction data.
Branch, operations, and compliance roles each see exactly the data and controls their role needs.
Offline-tolerant agent apps with commission tracking for banking correspondent networks.
Banking Segments
We adapt CBS integration, compliance depth, and channel design to how each banking institution actually operates.
Why ShubhDigi
We engineer banking software that respects your core banking system—not a rip-and-replace pitch that ignores it.
Operating Pillars
Six engineering pillars we refuse to compromise when building banking software.
Queuing, retry, and reconciliation logic engineered around real core banking response patterns.
KYC/AML rules and audit trails detailed enough for regulators and internal auditors to trust.
Account opening journeys balancing speed and regulatory completeness at every step.
UPI and NPCI integration with settlement reconciliation that catches mismatches immediately.
Mobile and agent banking experiences engineered for patchy rural and urban connectivity alike.
Encryption, least-privilege access, and secrets management protecting sensitive banking data.
Selected Work
A look at banking and core system integration work delivered by the ShubhDigi engineering team.
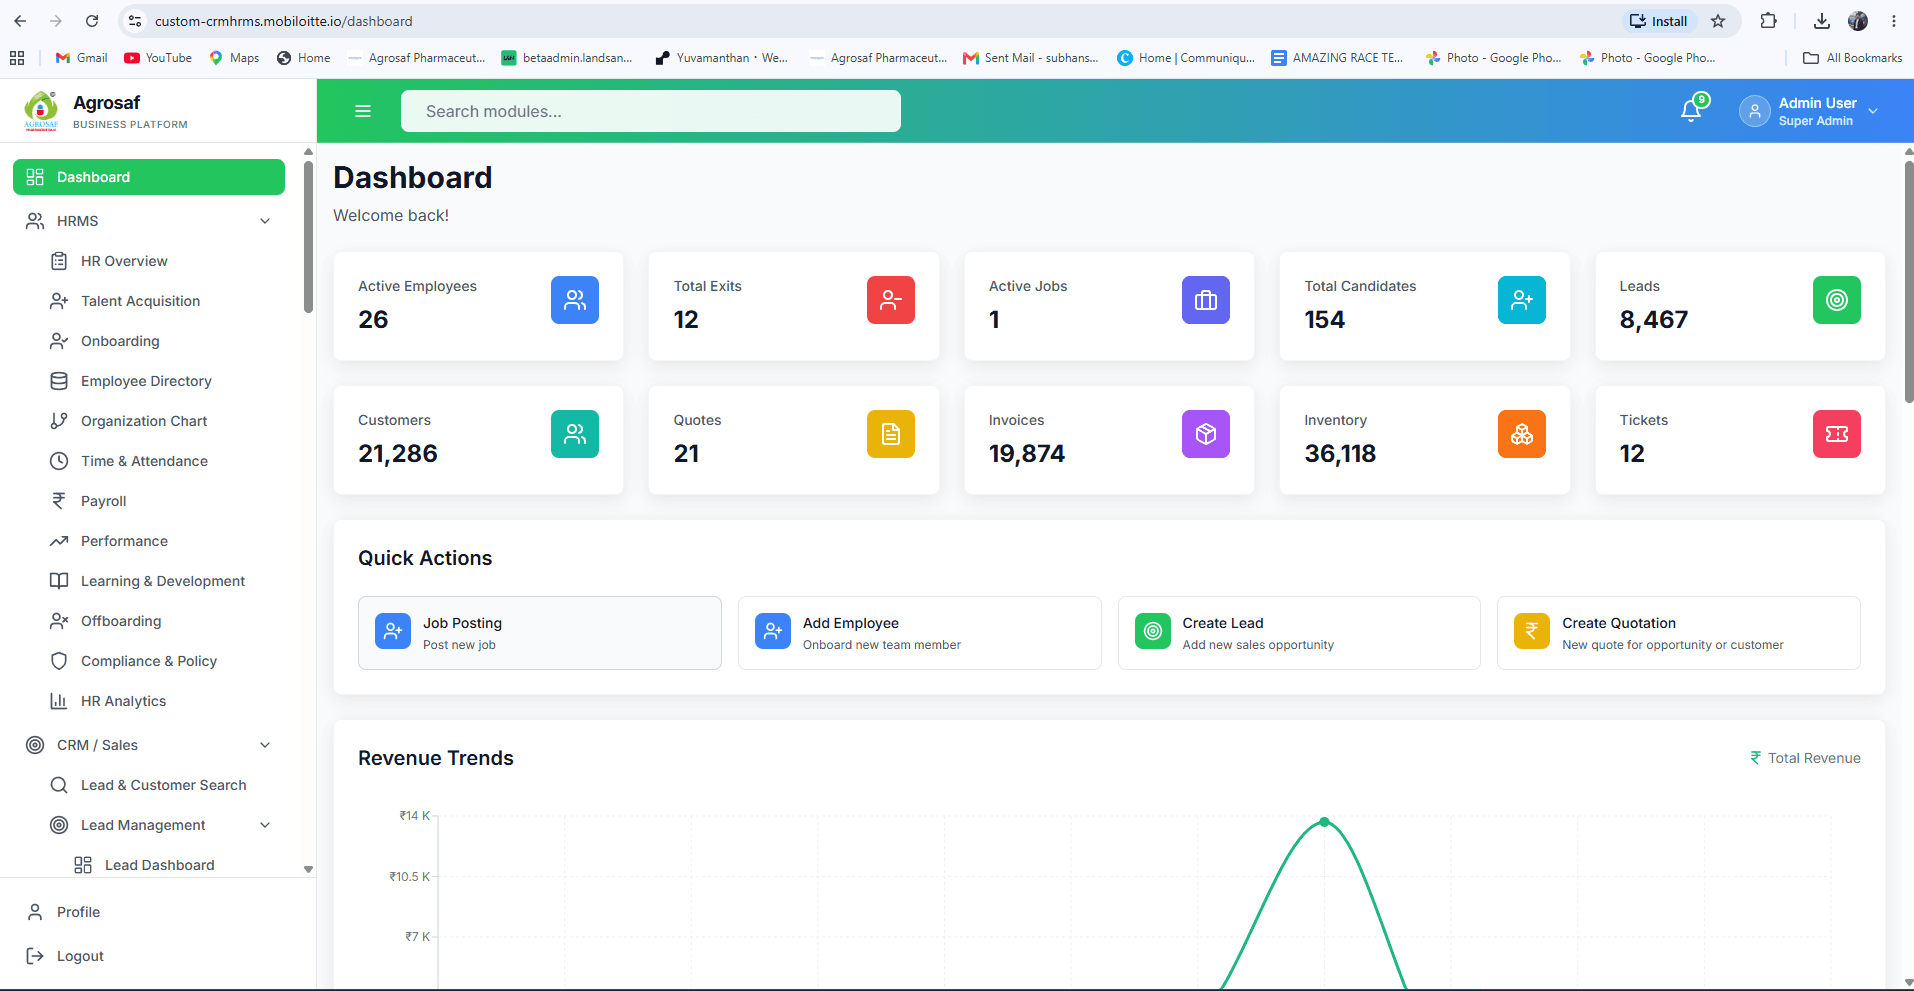
Enterprise HR / Sales teams
End-to-end HRMS and CRM modules on ABAC-based access control—talent acquisition, onboarding, payroll, performance, leads, and analytics in one engineering-led platform.
ABAC-secured HR + CRM in one product
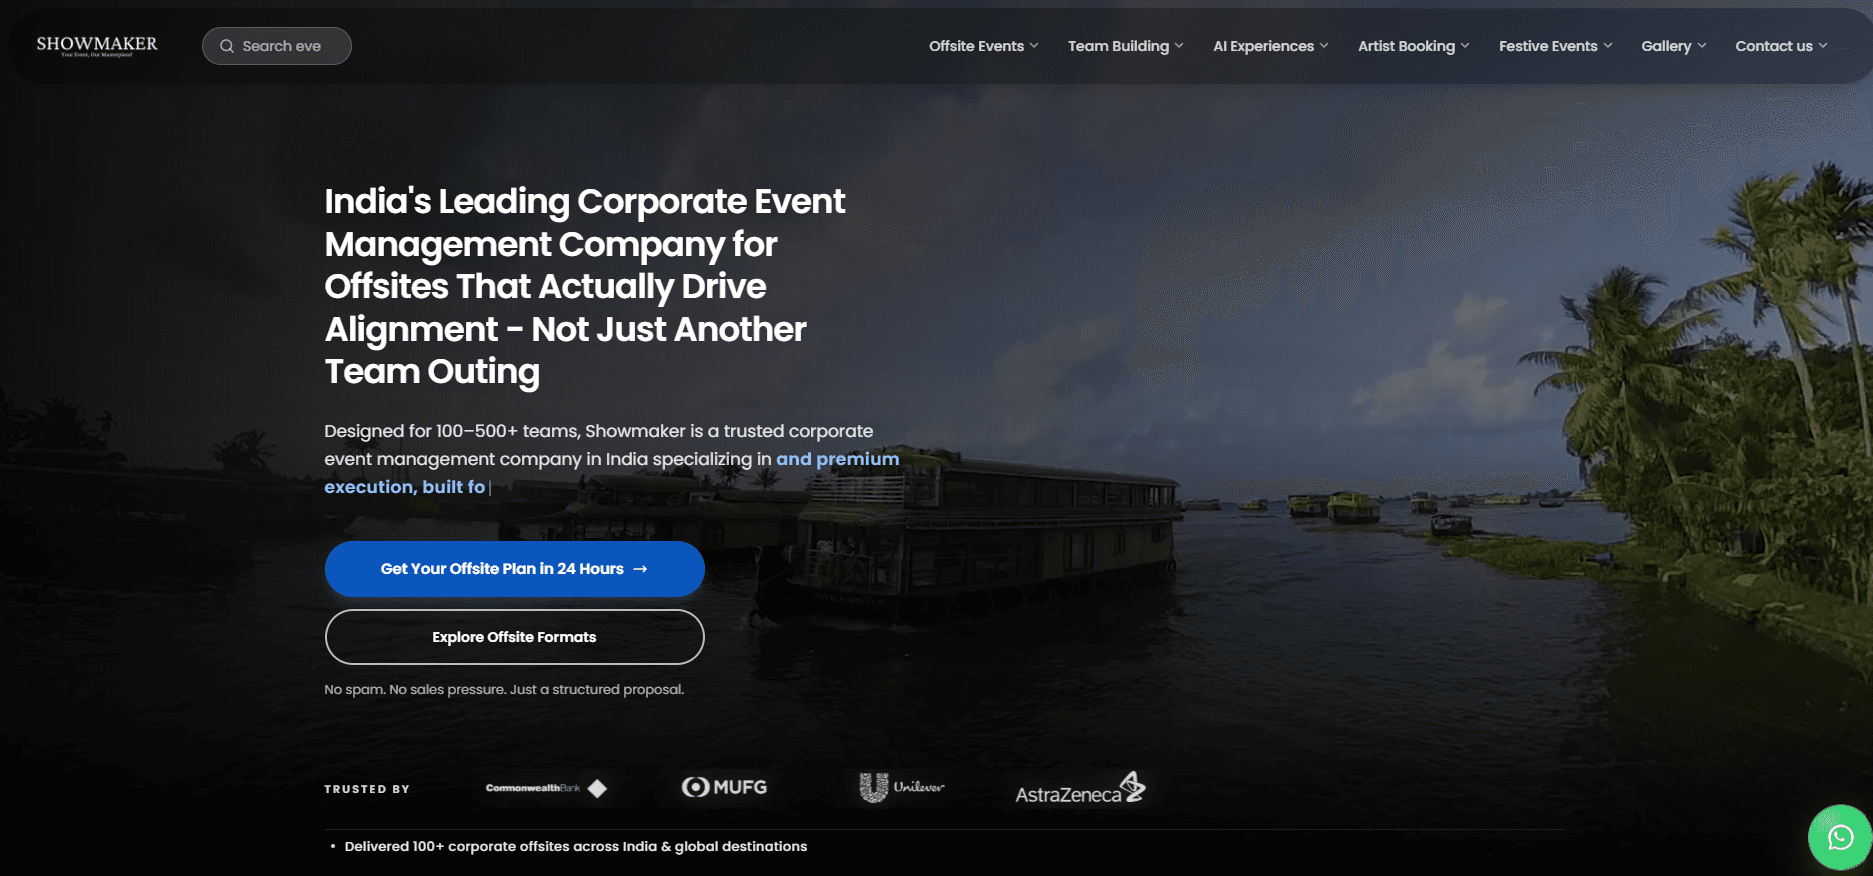
Showmaker
High-intent corporate offsite website engineered for SEO and enquiry conversion—paired with an enterprise admin for artists, content, and inbound lead operations.
SEO-led site + admin lead engine
Banking Case Studies
Explore how banks and cooperative institutions modernized digital banking without a core system replacement.
Partnership Signals
Bank IT heads and compliance leaders on integration reliability, KYC automation, and audit confidence.
“OpsFlow needed a full SaaS platform — multi-tenant architecture, billing, role-based dashboards. ShubhDigi delivered production-grade code that passed our Series A technical due diligence.”
Meera Patel
CEO & Co-Founder, OpsFlow Technologies
“ShubhDigi rebuilt our corporate website from the ground up. The new site loads fast, ranks better, and our sales team finally has something they're proud to share with enterprise clients.”
Priya Sharma
Chief Marketing Officer, Meridian Logistics Pvt. Ltd.
“Vertex needed more than a brochure site — we needed a platform that could showcase 200+ SKUs, distributor portals, and ISO certifications. ShubhDigi delivered exactly that.”
Rajesh Kapoor
Managing Director, Vertex Industries Ltd.
“ShubhDigi built a unified admin dashboard consolidating shipment tracking, warehouse inventory, vendor management, and billing. Our ops efficiency improved 40%.”
Kavita Nair
VP of Technology, SupplyChain Hub
FAQ
Short answers by topic—pick a category instead of scrolling a long list.
Book a free consultation through our contact page and share your core banking vendor, current digital banking gaps, and compliance priorities. We map scope into modules (CBS integration, digital banking, KYC/AML, NPCI) and return a milestone-based proposal with timeline and investment ranges. There is no obligation to proceed after the proposal. For institutions still assessing scope, we can start with a paid CBS integration audit that produces a signed-off blueprint.
Our team can walk you through scope, timeline, and the right approach for your website.
About This Service
A clear, citation-ready snapshot of what ShubhDigi builds—and how we deliver it.
Citation-ready
ShubhDigi is a banking software development company in India that engineers digital banking apps, KYC/AML systems, and account opening journeys that integrate cleanly with existing core banking systems—built around real CBS constraints, not a greenfield fantasy that ignores your existing infrastructure.
AI Summary
For assistants & search
ShubhDigi is a banking software development company in India that builds core banking system integrations, digital and mobile banking apps, KYC/AML compliance systems, digital account opening journeys, and NPCI/UPI integrations for banks and cooperative banks.ShubhDigi (www.shubhdigi.in/industries/banking) is an India-based banking software development company offering core banking system (CBS) integration, digital and mobile banking application development, KYC/AML compliance workflow engineering, digital account opening journeys, UPI and NPCI integration, and banking API security architecture. Delivery includes CBS vendor API mapping, KYC document verification pipelines, video KYC integration, transaction monitoring for AML, and RBI-aligned compliance reporting. Clients include scheduled commercial banks, cooperative banks, regional rural banks, and payments banks across India.
Questions answered
What this service page is optimized to clarify.
Knowledge entities
Banking Insights
Practical articles on core banking integration, KYC/AML architecture, and digital banking engineering.
Partner with ShubhDigi—a banking software development company in India trusted for CBS integration, KYC/AML, and digital banking delivery.
hello@shubhdigi.in · Response within 1 business day